SFC Updates
CY
24 October 2026
證監會強化首次公開招股與企業失當行為打擊力度:多管齊下守護香港資本市場廉潔穩健 SFC Steps Up Crackdown on IPO and Corporate Misconduct: A Multi-Pronged Approach to Safeguarding Hong Kong's Capital Market Integrity
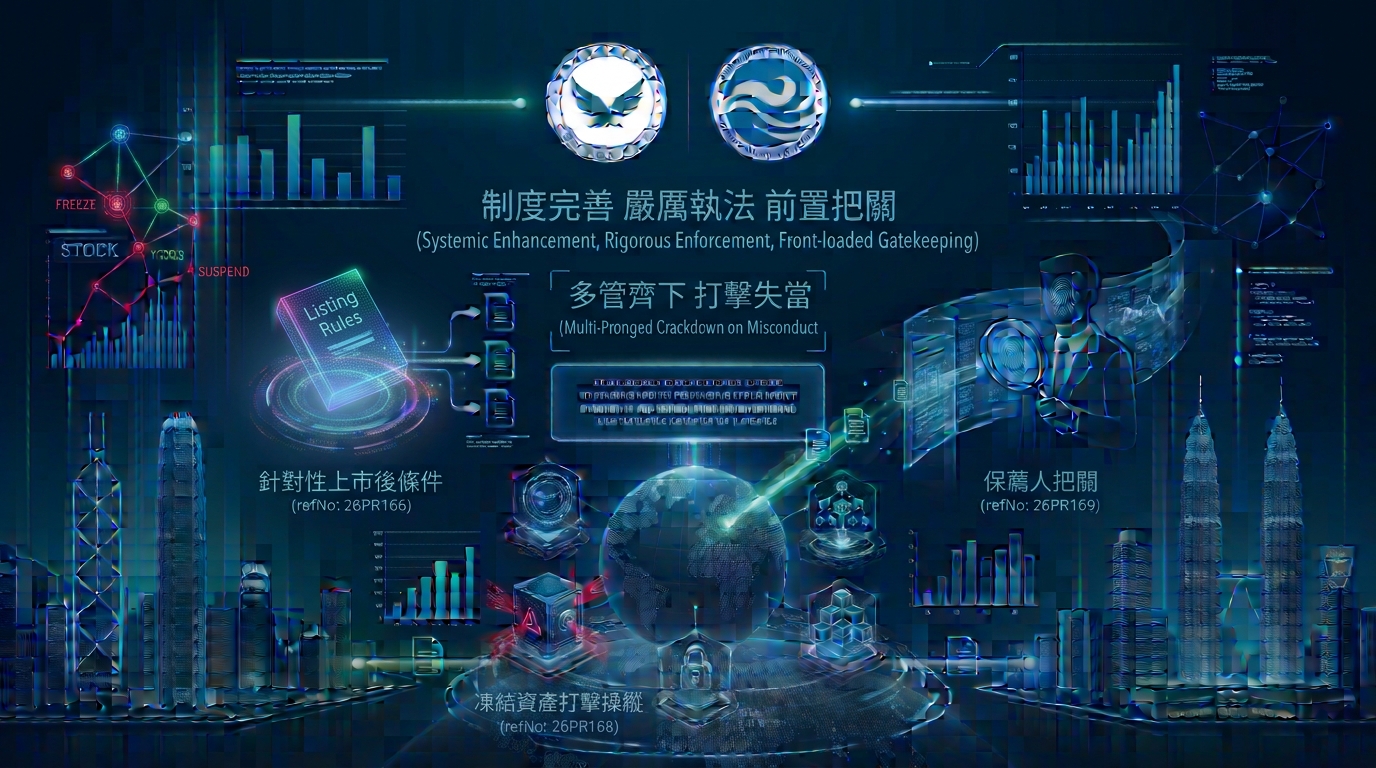
香港證券及期貨事務監察委員會(證監會)近期發布一系列重要監管公布與執法行動,涵蓋修訂《證券市場上市規則》以引入具針對性的上市後條件與獨立覆核機制(refNo: 26PR165)、對涉嫌操縱首次公開招股(IPO)的兩個集團採取重拳打擊並凍結資產及暫停「茶百道」股份交易(refNo: 26PR168),以及發布通函肯定保薦人工作改善並敦促中介人警惕IPO不透明資金安排(refNo: 26PR169)。這一系列組合拳彰顯了證監會從制度完善、嚴厲執法到前置把關的全方位監管決心。
The Securities and Futures Commission (SFC) recently released a series of significant regulatory announcements and enforcement actions, including amending the Rules Governing the Listing of Securities on the Stock Exchange of Hong Kong to introduce targeted post-listing conditions and independent review mechanisms (refNo: 26PR165), taking decisive enforcement action against two suspected IPO manipulation syndicates by freezing assets and suspending trading in ChaPanda shares (refNo: 26PR168), and issuing a circular noting improvements in sponsor work while urging intermediaries to remain vigilant against opaque IPO funding arrangements (refNo: 26PR169). This coordinated regulatory push underscores the SFC's comprehensive commitment spanning systemic enhancement, rigorous enforcement, and front-loaded gatekeeping.
一、 內容摘要 / 要点总结 (Summary of Key Highlights)
1. 賦權引入針對性上市後條件與獨立覆核機制 (Empowering Targeted Post-Listing Conditions and Independent Review Mechanism)
證監會發表諮詢總結,落實修訂《證券及期貨(在證券市場上市)規則》,預計於2027年第一季生效。修訂將容許證監會在上市前後施加持續適用的條件,作為暫停交易以外的替代方案,並引入由證券及期貨事務上訴審裁處進行獨立覆核的新機制,以提升程序公義。
The SFC published its consultation conclusions to amend the Securities and Futures (Stock Market Listing) Rules, anticipated to take effect in the first quarter of 2027. The amendments will empower the SFC to impose ongoing post-listing conditions as alternatives to immediate trading suspensions, while introducing an independent review mechanism by the Securities and Futures Appeals Tribunal to enhance procedural fairness.
2. 重拳打擊涉嫌操縱IPO集團,凍結鉅額資產並暫停茶百道交易 (Cracking Down on Suspected IPO Manipulation Syndicates with Asset Freezes and Trading Suspension)
證監會對兩個涉嫌透過欺詐計劃營造虛假IPO股份需求的集團採取行動,向多家經紀行發出限制通知書,凍結合共逾46億港元資產,並依據上市規則第8(1)條指示聯交所暫停四川百茶百道實業股份有限公司(茶百道)的股份交易。
The SFC took action against two syndicates allegedly involved in fraudulent schemes to fabricate IPO demand, issuing restriction notices to multiple brokerages to freeze over HK$4.6 billion in assets and directing the HKEX to suspend trading in Sichuan ChaPanda Industrial Co., Ltd. (ChaPanda) under section 8(1) of the Stock Market Listing Rules.
3. 肯定保薦人工作改善成效,敦促把關者提防不透明資金安排 (Acknowledging Sponsor Progress and Urging Gatekeeper Vigilance Against Opaque Funding)
證監會發布通函指出,自今年1月以來保薦人資源及主要人員工作量已見顯著改善,但同時警告市場警惕潛在的預警跡象,包括上市前後的巨額資金往來及可能掩飾最終投資者身分的可疑安排,合力防範市場扭曲。
A SFC circular noted that sponsor resources and key personnel workloads have markedly improved since January, while warning the market to remain alert to potential red flags, including substantial pre-or-post-listing fund flows and suspicious arrangements masking ultimate investors, to prevent market distortion.
二、 觀察與解析 (Insights)
1. 完善監管工具箱,實現從「一刀切」到「精準治理」的範式轉變 (Upgrading the Regulatory Toolbox: Transitioning from Blanket Approaches to Precision Governance)
傳統上,監管機構面對上市後嚴重違規或風險時往往依賴全面停牌,這對市場流動性與中小投資者造成一定震動。透過引入靈活的上市後條件與替代暫停交易方案,證監會在維持市場秩序與保障流動性之間取得了更具彈性的平衡,體現了現代化監管的成熟與務實。
Traditionally, regulators relied heavily on blanket trading suspensions when addressing post-listing irregularities, which often disrupted market liquidity and minor shareholders. By introducing flexible post-listing conditions and alternatives to suspension, the SFC strikes a more resilient balance between maintaining market order and preserving liquidity, reflecting the maturity and pragmatism of modern regulation.
2. 零容忍打擊IPO造假與利益輸送,築牢市場廉潔防線 (Zero-Tolerance Enforcement Against IPO Fraud and Tunneling to Secure Market Integrity)
凍結高達數十億元的涉案資產及果斷暫停問題股份交易,展示了證監會打擊資本市場「毒瘤」的強硬姿態。部分IPO所得款項透過隱蔽協議回流至承配人的安排嚴重侵蝕價格發現功能,執法重拳直擊利益鏈條核心,有助於重塑市場公信力。
Freezing billions in tainted assets and decisively suspending compromised stocks demonstrate the SFC's uncompromising stance against market malignancies. The illicit diversion of IPO proceeds through covert back-channel agreements severely erodes price discovery, and targeted enforcement hitting the core of these chains helps rebuild market credibility.
3. 推動保薦人主體責任落地,實現「機構自治」與「外部監管」共振 (Promoting Sponsor Accountability: Synergy Between Institutional Self-Governance and External Regulation)
數據顯示保薦人項目分配更趨均衡且工作過載顯著緩解,說明行業在監管引導下正朝高質量方向深化治理。然而,證監會持續發出預警並對違規保持高壓,表明壓實中介人作為「把關者」的首要責任仍是防範系統性風險的重中之重,唯有中介機構保持高度職業懷疑,方能從源頭阻斷欺詐風險。
Data showing more balanced workload distribution among sponsors indicates that the industry is deepening governance toward higher quality under regulatory guidance. Nonetheless, persistent SFC warnings highlight that reinforcing intermediaries' primary gatekeeping role remains vital for systemic risk prevention, as only through professional skepticism can fraud risks be intercepted at the source.
原文链接 (Sources):
* [https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR165](https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR165)
* [https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR168](https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR168)
* [https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR169](https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR169)
免责声明 / Disclaimer
本文仅作为一般概述,旨在提供信息参考,并基于有关证监会通函的公开资料编写。它不构成任何法律、监管、合规或专业建议。读者不应依赖本概述来代替审阅完整的官方通函及相关文件,亦不应代替寻求合格专业人士的独立意见。文中所载资料可能并不完整或并非最新,且监管要求可能会发生变化。对于基于本文内容所采取的任何行动或引起的任何遗漏,概不承担任何法律责任。持牌实体应直接咨询证监会或其自身的法律/合规顾问以获取具体指引。
This article is a general summary prepared for informational purposes only and is based on publicly available information regarding the SFC circulars. It does not constitute legal, regulatory, compliance, or professional advice. Readers should not rely on this summary as a substitute for reviewing the full official circulars and associated documents or obtaining independent advice from qualified professionals. The information may not be complete or up to date, and regulatory requirements can change. No liability is accepted for any actions taken or omissions based on this content. Licensed entities should consult the SFC directly or their own legal/compliance advisors for specific guidance.