SFC Updates
CY
2 August 2026
香港证监会7月执纪行动之总结与观察Summary and Analysis of the SFC July Disciplinary Actions
一、 7月证监会处罚重点 Summary of July's disciplinary actions
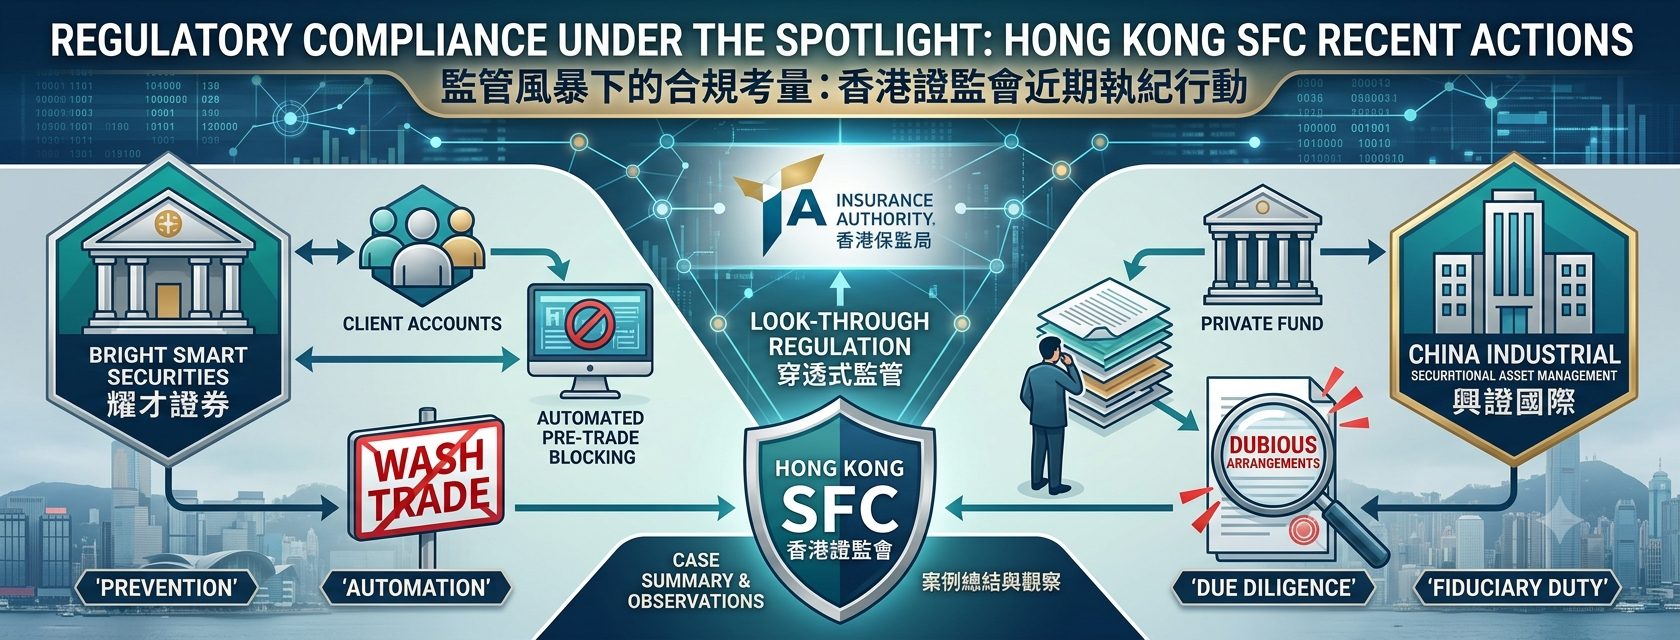
香港证券及期货事务监察委员会(证监会,SFC)于近日(2026年7月27日)连续公布了两项针对持牌金融机构的纪律处分决定,分别涉及零售经纪商耀才证券国际(香港)有限公司(耀才证券)以及持牌资管机构兴证国际资产管理有限公司(兴证国际资管)。这两起案例分别聚焦于“经纪商市场监控漏洞”与“资产管理人的通道化及尽职调查缺失”,集中反映了香港监管机构对维护市场廉洁稳健与保护投资者利益的坚定立场。The Securities and Futures Commission (SFC) of Hong Kong recently (27 July 2026) announced two disciplinary actions against licensed financial institutions, targeting retail brokerage Bright Smart Securities International (Hong Kong) Limited (Bright Smart Securities) and licensed asset manager China Industrial Securities International Asset Management Limited (CISIAM). Focusing respectively on "brokerage market monitoring loopholes" and "asset manager 'conduit' risks and lack of due diligence," these two cases underscore the regulator's firm stance on preserving market integrity and protecting investor interests.
根据证监会公布的信息,耀才证券因未能实施充足且有效的内部监控程序以监察及侦测客户的清洗交易(Wash Trades),被予以公开谴责并处以280万港元罚款;而兴证国际资管则因在管理某私募基金期间,未能有效识别及处理可疑投资安排中的红旗警告(Red Flags),未能履行独立投资判断与尽职调查职责,被公开谴责并处以680万港元罚款。
According to official SFC disclosures, Bright Smart Securities was reprimanded and fined HK$2.8 million for failing to implement adequate and effective internal control procedures to monitor and detect wash trades conducted by clients. Meanwhile, CISIAM was reprimanded and fined HK$6.8 million for failing to properly identify and address red flags in suspicious investment arrangements while managing a private fund, as well as failing to exercise independent investment discretion and conduct due diligence.
二、 案例要点剖析 | Detailed Case Breakdown
1. 耀才证券案:交易监控漏洞与清洗交易防范缺失 | Bright Smart Securities Case: Vulnerabilities in Trade Monitoring and Failure to Prevent Wash Trades
在2023年11月1日至2025年9月13日期间,耀才证券因内部监控措施不足,导致615个客户账户执行了1,021对涉及736只股票及权证的清洗交易。清洗交易是指不涉及股份实益拥有权改变的买卖行为,易造成市场交易活跃的虚假表象,从而扭曲真实的供求关系。Between 1 November 2023 and 13 September 2025, deficiencies in Bright Smart Securities' internal controls resulted in 1,021 pairs of wash trades executed across 615 client accounts involving 736 stocks and warrants. Wash trades involve transactions where there is no change in beneficial ownership, creating a false or misleading appearance of active trading and distorting genuine market supply and demand.
证监会调查指出,耀才证券在2024年3月前过度依赖事后监控与人工审查,未能防范未然。即使后续引入了事前拦截机制,该机制仍高度依赖人工介入而非自动化拦截,且阻截逻辑仅在“再次侦测到清洗交易”后方被触发;同时,同一客户单日内的多次违规交易被归为单一事件,导致客户能够在同一交易日内无限制地重复进行清洗交易。
The SFC’s investigation revealed that prior to March 2024, Bright Smart Securities relied heavily on post-trade monitoring and manual reviews, failing to prevent market misconduct beforehand. Even after introducing pre-trade blocking arrangements in March 2024, the system still relied on manual intervention rather than automated blocking, and its mechanism was triggered only after a wash trade was detected again. Furthermore, multiple wash trades within a single account per day were treated as a single event, allowing clients to repeatedly execute wash trades within the same trading day without constraint.
2. 兴证国际资管案:私募基金“通道化”疑云与尽职调查缺失 | CISIAM Case: "Conduit" Risks in Private Fund Management and Lack of Due Diligence
在2019年8月至2020年9月期间,兴证国际资管受香港授权保险公司泰禾人寿(Tahoe Life)的首席投资官要求,为其设立并管理一所私募基金。在管理过程中,兴证国际资管按照客户指示安排了一系列结构复杂且缺乏明确商业合理性的投资交易,包括购买与泰禾人寿关联公司债务工具挂钩的结构性票据,并将其转让至其他机构管理的基金中。
Between August 2019 and September 2020, CISIAM established and managed a private fund for Tahoe Life Insurance Company Limited (Tahoe Life), an authorized insurer in Hong Kong, at the request of Tahoe Life's Chief Investment Officer. During its management, CISIAM entered into a series of overly complex investment arrangements lacking clear commercial rationale at the client's request, including purchasing structured notes linked to debt instruments issued by a related company of Tahoe Life and subsequently transferring them to another fund managed by a different manager.
证监会强调,此类交易安排不仅增加了不必要的交易成本与风险,更存在隐匿资产流动及关联交易的嫌疑。兴证国际资管在面对多重明确的预警信号(Red Flags)时,未能进行深入的独立调查与合规审查,沦为协助客户进行违规操作的“通道”(Conduit)。此外,该基金的实际投资亦偏离了其既定的投资限制与目标,风险管理与监控机制严重失效。
The SFC emphasized that such arrangements unnecessarily increased transaction costs and risks, while raising serious concerns about concealing asset movements or connected party transactions. Despite multiple clear red flags, CISIAM failed to conduct in-depth independent inquiries or compliance reviews, effectively allowing its services to be used as a "conduit" for improper conduct. Additionally, the fund's actual investments departed from its stated investment restrictions and objectives, revealing severe failures in risk management and monitoring.
三、 行业启示 Market Implications
1. 事前自动化风控是零售经纪商合规的底层硬要求 | Automated Pre-Trade Controls as a Fundamental Requirement for Retail Brokers
从耀才证券案可以看出,监管机构对券商“交易监控”的标准正全面升级。仅仅依赖事后抽查(Post-trade Review)或人工主导的防御体系已无法满足现代高频、高并发交易环境下的合规要求。券商必须建立全流程、自动化的事前阻截(Pre-trade Automated Risk Management)机制,特别是在识别洗售交易、异常订单匹配等市场操纵行为上,系统算法的实时防范能力将成为合规审查的核心考量指标。
The Bright Smart Securities case demonstrates that regulatory standards for trade surveillance are undergoing a comprehensive upgrade. Relying solely on post-trade sampling or manual defense mechanisms can no longer satisfy compliance requirements in today's high-frequency, high-volume trading environment. Brokerages must establish automated, end-to-end pre-trade blocking systems. In identifying market manipulation like wash trades or suspicious order matching, the real-time preventive capability of system algorithms has become a key metrics of compliance evaluations.
2. 杜绝“通道化”履职,恪守资产管理人的受托责任 | Eradicating "Conduit" Practices to Uphold Fiduciary Duty in Asset Management
兴证国际资管案则给中资及广阔市场的持牌资管机构敲响了警钟。在私募基金管理中,资产管理人绝非单纯的“指令执行者”,而是承担着严格受托责任(Fiduciary Duty)的独立投资决策方。无论客户(特别是单一结构性大客户)提出何种投资要求,持牌资管均须独立评估交易的商业合理性、真实目的及潜在风险。若盲目跟从客户指令而忽视红旗警告,将面临严厉的法规制裁与声誉风险。
The CISIAM case serves as a stark warning to licensed asset managers, particularly PRC-backed firms and those in the broader market. In managing private funds, asset managers are independent investment decision-makers bound by strict fiduciary duties, rather than passive "order-executors." Regardless of client demands—especially from major structural investors—licensed managers must independently evaluate commercial rationale, true intent, and potential risks. Blindly following client instructions while turning a blind eye to red flags will inevitably invite severe regulatory sanctions and reputational damage.
3. 跨机构与跨部门联合监管常态化,市场打假力度持续提升 | Cross-Agency Regulatory Collaboration Normalizes as Market Enforcement Intensifies
值得注意的是,兴证国际资管案源于香港保险业监管局(保监局,IA)与香港证监会(SFC)之间的跨机构情报共享与监管协同。此前,保监局已就相关违规关联交易对泰禾人寿作出了公开谴责及1,000万港元的裁罚。这表明香港各监管部门(证监会、金管局、保监局)之间的穿透式监管(Look-through Regulation)与信息互通已趋向常态化,任何企图利用跨行业、跨机构复杂结构来掩盖真实资金流向与不当行为的手法,在当前监管网络下均将无所遁形。
Notably, the CISIAM enforcement action stemmed from cross-agency information sharing and joint oversight between Hong Kong's Insurance Authority (IA) and the SFC. Previously, the IA had publicly reprimanded Tahoe Life and imposed a HK$10 million fine for related party transaction non-compliance. This highlights that look-through regulation and inter-agency collaboration among Hong Kong regulators (SFC, HKMA, IA) have become standard practice. Attempts to utilize cross-sector or inter-entity complex structures to conceal fund flows or improper activities will face inescapable scrutiny under today's regulatory network.
原文(Source):
https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR117
https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR116
免责声明 / Disclaimer
本文仅作为一般概述,旨在提供信息参考,并基于有关证监会通函的公开资料编写。它不构成任何法律、监管、合规或专业建议。读者不应依赖本概述来代替审阅完整的官方通函及相关文件,亦不应代替寻求合格专业人士的独立意见。文中所载资料可能并不完整或并非最新,且监管要求可能会发生变化。对于基于本文内容所采取的任何行动或引起的任何遗漏,概不承担任何法律责任。持牌实体应直接咨询证监会或其自身的法律/合规顾问以获取具体指引。
This article is a general summary prepared for informational purposes only and is based on publicly available information regarding the SFC circulars. It does not constitute legal, regulatory, compliance, or professional advice. Readers should not rely on this summary as a substitute for reviewing the full official circulars and associated documents or obtaining independent advice from qualified professionals. The information may not be complete or up to date, and regulatory requirements can change. No liability is accepted for any actions taken or omissions based on this content. Licensed entities should consult the SFC directly or their own legal/compliance advisors for specific guidance.