Market Updates
CY
26 July 2026
证监会优化单日杠杆及反向产品监管框架总结与观察 Summary and Observation of SFC enhances regulatory framework for daily leveraged and inverse products
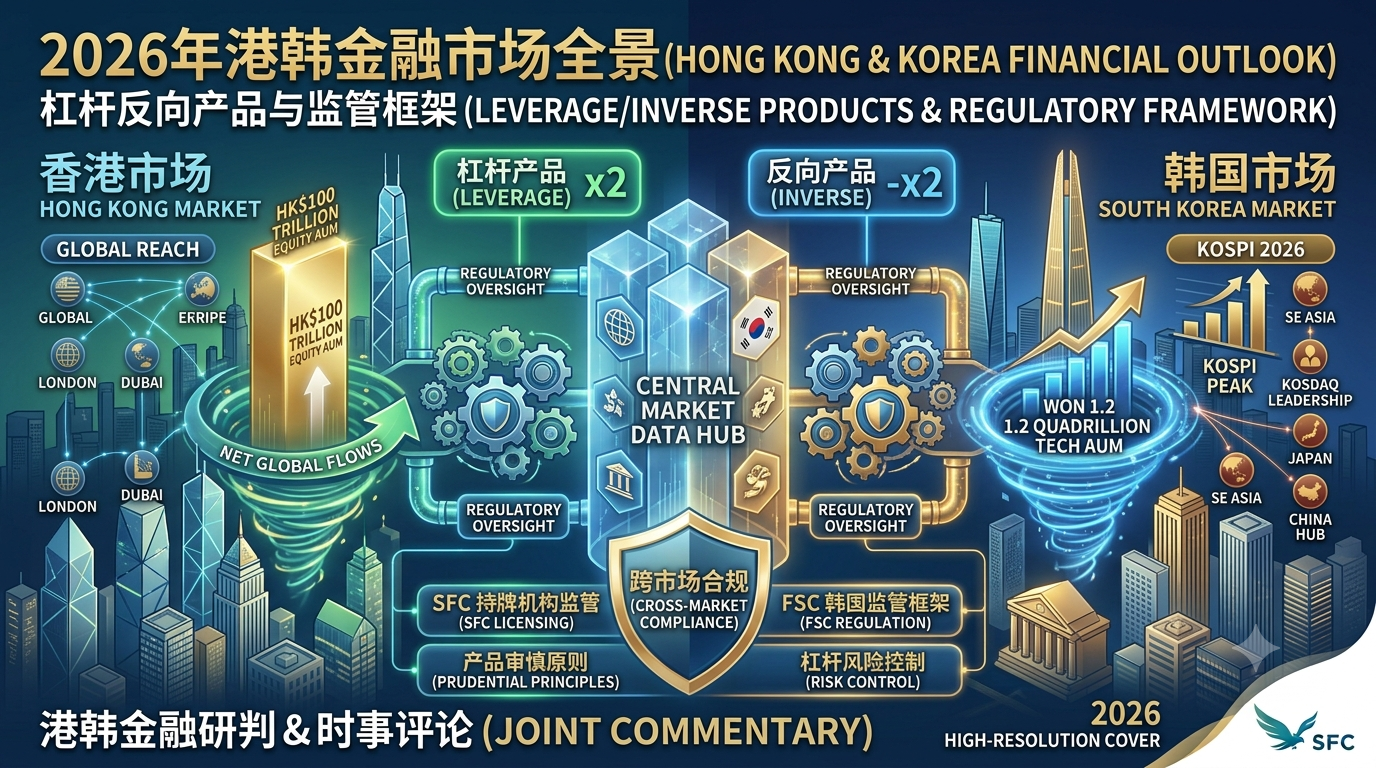
证券及期货事务监察委员会(证监会)7月24日发布《有關上市結構性基金的修订通函》,旨在优化认可杠杆及反向产品的监管框架,让产品提供者能更灵活地管理其产品,同时提醒投资者该等产品作为单日交易工具的特性,以下为要点总结及观察。
On July 24, the Securities and Futures Commission (SFC) issued a "Circular on Amendments to Listed Structured Funds." The circular aims to refine the regulatory framework for authorized leveraged and inverse products, allowing product providers greater flexibility in managing their products, while also reminding investors of the nature of these products as instruments for single-day trading. A summary of key points and observations follows.
一、 要点总结 (Summary of Key Highlights)
1. 监管背景与市场动态 (Regulatory Context & Market Dynamics)
香港证券及期货事务监察委员会(证监会,SFC)于2026年7月24日发出经修订的通函,优化认可杠杆及反向产品(L&I Products)的监管框架。自2026年初以来,受个股杠杆及反向产品(Single Stock L&I Products)迅猛发展的推动,香港L&I产品市场规模显着扩大。此类产品高度依赖标的个股生态系统的流动性与衍生品对冲工具来维持杠杆敞口,市场环境正面临日益复杂的容量限制。
On July 24, 2026, the Securities and Futures Commission (SFC) issued a revised circular to enhance the regulatory framework for authorised Leveraged and Inverse (L&I) Products. Since early 2026, Hong Kong's L&I products market has grown significantly, primarily propelled by the rapid expansion of Single Stock L&I Products. These instruments increasingly rely on the liquidity and derivative ecosystems of underlying equities to maintain targeted leverage exposures, giving rise to growing capacity constraints under dynamic market conditions.
2. 引入“灵活杠杆结构”机制 (Introduction of the "Flexible Leverage Structure")
为应对市况快速变化对产品容量(Capacity)的冲击,证监会规定容量受限的L&I产品须采用“灵活杠杆结构”。在该机制下,产品提供者可在现有法定上限(杠杆产品2倍,反向产品-2倍)以内,每日动态调整杠杆倍数。在极高交易量或流动性紧缩期间,发行商可主动下调目标杠杆倍数,从而降低跟跟踪偏离度(Tracking Error)及清算风险,确保产品有序运作。
To address the impact of market volatility on product capacity, the SFC mandates that L&I products with capacity highly sensitive to market changes adopt a "Flexible Leverage Structure." Under this mechanism, product providers may dynamically adjust the leverage ratio daily within existing regulatory caps (up to 2x for leveraged products and -2x for inverse products). During periods of extreme volume or liquidity tightness, issuers can proactively reduce targeted leverage ratios to mitigate tracking error and settlement risks, ensuring orderly market operations.
3. 信息披露与命名合规要求 (Transparency & Product Naming Mandates)
为保障投资者知情权,证监会要求产品提供者必须在每日收市后,通过其官方网站及香港交易所(HKEX)网站披露下一交易日的目标杠杆倍数。同时,产品的法定名称必须清晰反映其“灵活杠杆”特征及最大杠杆上限。海外市场的杠杆及反向ETF通常已具备类似的动态调整弹性,此次改动使香港监管标准与国际惯例进一步接轨。
To safeguard investor awareness, the SFC requires product providers to disclose the target leverage ratio for the upcoming trading day on both their official websites and the HKEX portal following the market close each day. Furthermore, product names must explicitly reflect the flexible leverage feature and the maximum leverage cap. Similar flexibility is commonly embedded in overseas leveraged and inverse ETFs, aligning Hong Kong’s framework with international market standards.
4. 投资者教育与风险警示 (Investor Education & Risk Warnings)
证监会投资产品部执行董事吴家俐女士强调,本次监管优化旨在适应市场演变并加强投资者保护。证监会特别提醒投资者,L&I产品本质上是“单日(Daily)交易和对冲工具”,并非为持有超过一日的复利持有设计。复利效应(Compounding Effect)可能导致长期持有的回报与标的资产走势出现严重偏离。监管层同步推出了以“D-A-I-L-Y”为主题的资讯图表与评估清单,呼吁投资者每日进行风险评估。
Ms. Christina Ng, Executive Director of Investment Products at the SFC, emphasized that these enhancements represent timely adjustments to foster sustainable market growth while maintaining robust investor safeguards. The SFC specifically cautioned investors that L&I products are designed purely as "daily trading and hedging instruments" rather than buy-and-hold investments. Compounding effects over extended holding periods can cause performance to deviate significantly from the underlying assets. In parallel, the regulator launched a "D-A-I-L-Y" themed infographic checklist, urging investors to evaluate their positions daily.
二、 观察 ( Insights)
1. 容量瓶颈下的风险化解与微观结构防线 (Mitigating Capacity Bottlenecks & Market Microstructure Risks)
个股杠杆及反向产品与传统的宽基指数(如恒生指数、科技指数)L&I产品有着本质差异:个股的掉期(Swap)敞口承运能力、期权持仓限额(Position Limits)以及尾盘再平衡(Rebalancing)的流动性汲取能力均存在物理上限。当个股出现剧烈波动或极高换手率时,发行商若硬性维持固定2倍杠杆,极易在收市前引发“追涨杀跌”的再平衡交易,进而挤压标的股票流动性并放大市场波动。引入灵活杠杆机制,实际上赋予了发行商防范套利挤压与流动性枯竭的“安全阀”。
Single Stock L&I Products differ fundamentally from broad-based index L&I tools: individual stocks face strict physical limits in swap counterparty capacity, options position limits, and end-of-day rebalancing market depth. During periods of heightened volatility or extreme turnover, rigidly forcing a fixed 2x leverage compels issuers into pro-cyclical rebalancing trades near market close, which exacerbates underlying equity volatility and drains liquidity. Implementing a flexible leverage framework effectively equips market makers with a vital "safety valve" to prevent liquidity squeezes and structural market dislocations.
2. 重塑投资者预期:打破“固定杠杆”的心理锚定 (Reshaping Investor Expectations: Dismantling Fixed-Leverage Bias)
在过去的产品生态中,零售投资者倾向于将L&I产品误认为长期方向性下注工具,忽视了波动性耗损(Volatility Drag)与每日再平衡带来的路径依赖效应。通过将杠杆倍数变为每日公布的“动态变量”,并在产品名称中强制标注,监管层巧妙地打破了投资者对“固定2倍/反向2倍”的心理锚定。这一改动不仅降低了因跟跟踪偏离而产生的合规与纠纷隐患,更在微观层面重塑了市场的风险认知。
Historically, retail investors frequently misconstrued L&I products as buy-and-hold directional bets, underestimating the impact of volatility drag and path-dependency inherent in daily rebalancing. By converting the leverage ratio into a daily disclosed "dynamic variable" and mandating its inclusion in product naming, the regulator cleverly dismantles the fixed-leverage cognitive bias among market participants. This structural shift not only reduces tracking error disputes and legal liabilities but also fundamentally recalibrates risk perception across the retail market.
3. 监管权衡:灵活性与市场透明度的博弈 (Regulatory Balance: Flexibility vs. Market Transparency)
从金融市场监管的角度来看,此次政策调整展现了极佳的中立性与平衡艺术。一方面,过度的规制(如直接对容量设限或暂停发牌)会扼杀金融创新与个股衍生品市场的深度;另一方面,放任自流则可能在黑天鹅事件中诱发系统性尾部风险。通过“发行商自主下调杠杆 + 强制每日收市后信息披露”的双轨机制,香港证监会在保留自由市场活力的同时,将跟跟踪风险的隐患转化为公开透明的市场信息,兼顾了市场效率与投资者保护。
From a regulatory architecture standpoint, this policy calibration demonstrates remarkable neutrality and balance. On one hand, overly restrictive mandates—such as imposing hard capacity caps or freezing product approvals—would stifle market innovation and liquidity in single-stock derivatives. On the other hand, a hands-off approach risks systemic tail events during market anomalies. By pairing operational flexibility for issuers with strict post-market transparency rules, the SFC successfully preserves market vitality while converting latent tracking risk into fully visible market information.
4. 监管权衡与离岸衍生品枢纽的长期竞争力 (Regulatory Balance & Enduring Competitiveness as an Offshore Derivatives Hub)
从金融市场监管的角度来看,本次调整展现了极高的制度智慧。相比于韩国等市场被迫采取行政干预(如直接暂停产品发行或硬性设限),香港证监会采取了“发行商自主下调杠杆 + 强制每日收市后信息披露”的微观审慎机制。海外主流市场(如美欧)的杠杆ETF早已普及类似的弹性管理,香港迅速跟进并优化框架,不仅保留了自由市场的交易活力,更将潜在的跟踪风险转化为透明的公开信息,进一步巩固了香港作为亚太区全天候风险管理及衍生品交易中心的长期核心竞争力。
From a market governance perspective, this policy calibration demonstrates sophisticated institutional design. In contrast to blunt administrative interventions seen in other markets—such as mandatory caps or listing freezes—the SFC opted for a micro-prudential framework pairing issuer-driven leverage adjustments with mandatory post-market transparency. This aligns Hong Kong with established practices in major US and European markets, preserving trading flexibility while converting latent tracking risk into transparent market data, ultimately reinforcing Hong Kong's long-term competitive edge as the Asia-Pacific's premier risk management and derivatives hub.
原文(Source):https://apps.sfc.hk/edistributionWeb/gateway/EN/news-and-announcements/news/doc?refNo=26PR115
免责声明 / Disclaimer
本文仅作为一般概述,旨在提供信息参考,并基于有关证监会通函的公开资料编写。它不构成任何法律、监管、合规或专业建议。读者不应依赖本概述来代替审阅完整的官方通函及相关文件,亦不应代替寻求合格专业人士的独立意见。文中所载资料可能并不完整或并非最新,且监管要求可能会发生变化。对于基于本文内容所采取的任何行动或引起的任何遗漏,概不承担任何法律责任。持牌实体应直接咨询证监会或其自身的法律/合规顾问以获取具体指引。
This article is a general summary prepared for informational purposes only and is based on publicly available information regarding the SFC circulars. It does not constitute legal, regulatory, compliance, or professional advice. Readers should not rely on this summary as a substitute for reviewing the full official circulars and associated documents or obtaining independent advice from qualified professionals. The information may not be complete or up to date, and regulatory requirements can change. No liability is accepted for any actions taken or omissions based on this content. Licensed entities should consult the SFC directly or their own legal/compliance advisors for specific guidance.