Market Updates
CY
3 October 2026
“港马”单一呈交安排,简化两地同步上市流程Hong Kong-Malaysia Single Submission Arrangement
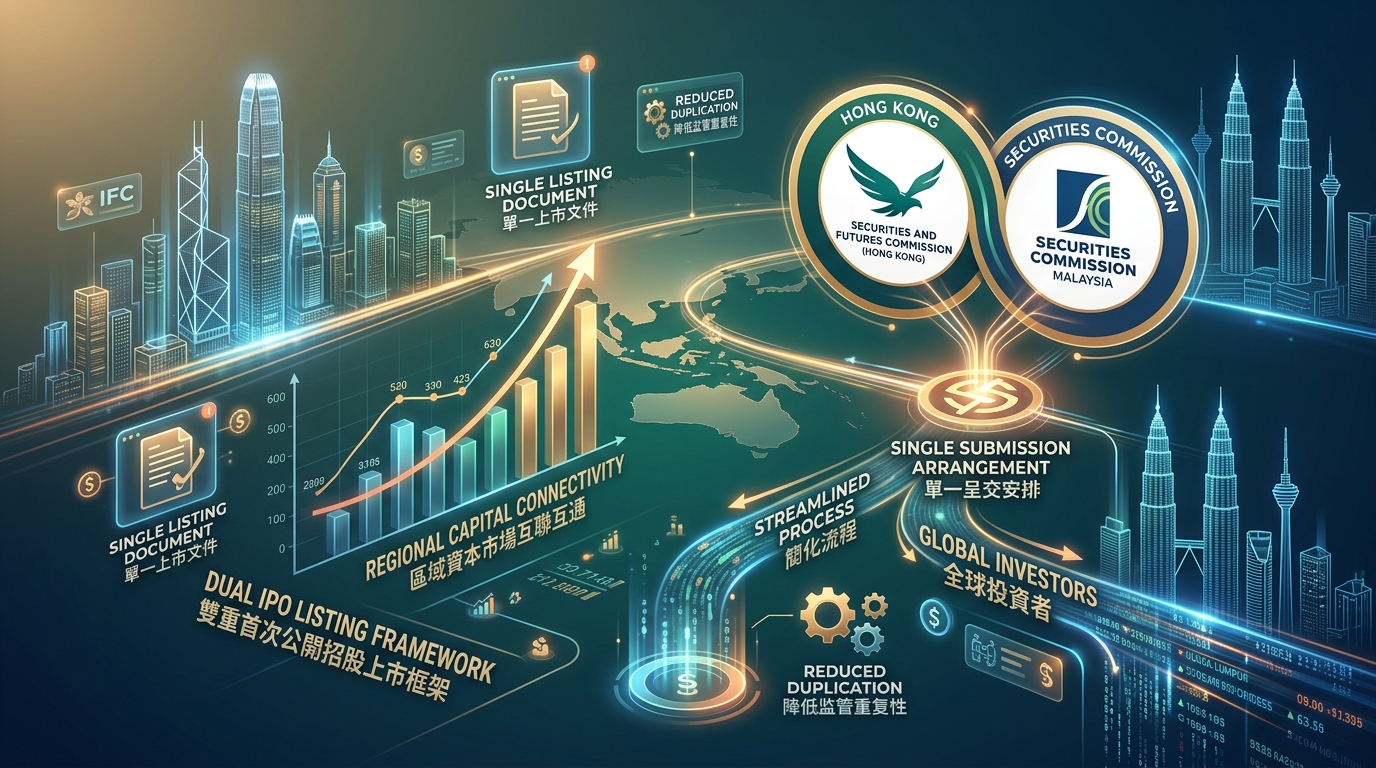
香港证券及期货事务监察委员会(证监会)与马来西亚证券委员会(马来西亚证监会)近日宣布推出“单一呈交安排”(Single Submission Arrangement),旨在简化香港与马来西亚两地同步上市(Simultaneous Listings)的监管及呈交程序。
The Securities and Futures Commission (SFC) of Hong Kong and the Securities Commission Malaysia (SC) recently announced the launch of the "Single Submission Arrangement" to streamline regulatory and submission procedures for simultaneous listings in both jurisdictions.
一、 內容摘要 / 要点总结 (Summary of Key Highlights)
1. 落实简化双重首次公开招股上市框架 (Operationalisation of Simplified Dual IPO Listing Framework)
单一呈交安排正式落实了双方于2026年7月23日签署的《谅解备忘录》中所设定的简化双重首次公开招股(IPO)上市框架,使有意在香港交易所主板或马来西亚证券交易所主板寻求主要上市并在另一市场同步寻求第二上市的企业能够享受更高效的流程。
The Single Submission Arrangement brings into operation the simplified dual IPO listing framework set out in the Memorandum of Understanding (MoU) signed by the two regulators on 23 July 2026, enabling enterprises seeking a primary listing on either the Main Board of the Stock Exchange of Hong Kong (SEHK) or the MAIN Market of Bursa Malaysia Securities Berhad, with a simultaneous secondary listing on the other market, to benefit from a more efficient process.
2. 实施单一上市文件与集中呈交 (Single Listing Document and Centralised Submission)
申请人只需呈交单一上市文件,即可同时满足两地市场的法定及上市要求;同时,申请人可通过集中、协调的途径提交上市申请,从而消除了在两个市场分别进行繁琐呈交的行政负担。
Applicants are only required to submit a single listing document to meet the statutory and listing requirements of both markets. At the same time, applicants may submit their listing applications through a centralised and coordinated channel, removing the administrative burden of separate submissions in both markets.
3. 设立专门双重上市审阅团队与协调审阅 (Dedicated Dual-Listing Review Teams and Coordinated Review)
两地监管机构已成立专门团队与沟通渠道,作为申请人及其顾问的直接联络点,并建立协调审阅机制以对齐时间表、尽量减少重复工作并简化针对申请人的提问。
Both regulatory bodies have established dedicated teams and communication channels to serve as direct contact points for applicants and their advisers, alongside a coordinated review mechanism to align timelines, minimise duplication, and streamline queries to applicants.
二、 觀察與解析 (Insights)
1. 深化东盟与香港区域资本市场互联互通 (Deepening ASEAN-Hong Kong Regional Capital Market Connectivity)
此项安排是落实前期《谅解备忘录》的务实且及时的后续举措,彰显了香港证监会与马来西亚证监会共同深化区域资本市场互联互通、实现互利共赢的共同愿景,也为区域企业开辟了更加通畅的跨境融资通道。
This arrangement represents a pragmatic and timely follow-up to the earlier MoU, demonstrating the shared vision of the SFC and the SC to deepen regional capital market connectivity for mutual prosperity and opening up smoother cross-border fundraising pathways for regional enterprises.
2. 大幅减省合规成本与行政负担 (Significant Reduction in Compliance Costs and Administrative Burdens)
通过整合申报文件并推行联合协调审阅,该机制有效避免了重复监管(Regulatory Duplication),显著降低了企业在IPO呈交阶段的合规成本与时间成本,增强了香港与马来西亚作为国际融资目的地的吸引力。
By consolidating application documents and implementing joint coordinated reviews, this mechanism effectively eliminates regulatory duplication, significantly lowering compliance and time costs for enterprises at the IPO application stage while enhancing the attractiveness of both Hong Kong and Malaysia as international fundraising destinations.
3. 兼顾资本活力与严谨投资者保障 (Balancing Capital Vitality with Robust Investor Protection)
在简化流程、便利企业对接更多元国际投资者及更深资金池的同时,两地监管机构依然坚守严格的合规标准及投资者保障原则,确保在提升区域资本配置效率的过程中不以牺牲监管质量为代价。
While streamlining processes to help businesses reach more diverse international investors and deeper pools of capital, the regulators remain steadfast in upholding rigorous compliance standards and investor protection principles, ensuring that enhanced regional capital allocation efficiency does not come at the expense of regulatory quality.
原文链接 (Source):[https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR159](https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR159)
免责声明 / Disclaimer
本文仅作为一般概述,旨在提供信息参考,并基于有关证监会通函的公开资料编写。它不构成任何法律、监管、合规或专业建议。读者不应依赖本概述来代替审阅完整的官方通函及相关文件,亦不应代替寻求合格专业人士的独立意见。文中所载资料可能并不完整或并非最新,且监管要求可能会发生变化。对于基于本文内容所采取的任何行动或引起的任何遗漏,概不承担任何法律责任。持牌实体应直接咨询证监会或其自身的法律/合规顾问以获取具体指引。
This article is a general summary prepared for informational purposes only and is based on publicly available information regarding the SFC circulars. It does not constitute legal, regulatory, compliance, or professional advice. Readers should not rely on this summary as a substitute for reviewing the full official circulars and associated documents or obtaining independent advice from qualified professionals. The information may not be complete or up to date, and regulatory requirements can change. No liability is accepted for any actions taken or omissions based on this content. Licensed entities should consult the SFC directly or their own legal/compliance advisors for specific guidance.